Does home insurance cover roof damage?
Usually yes for sudden storm damage, usually no for wear and tear. How insurers decide, and what to do before you claim. Storm damage? Call me 24/7.

No call-out charge, day or night
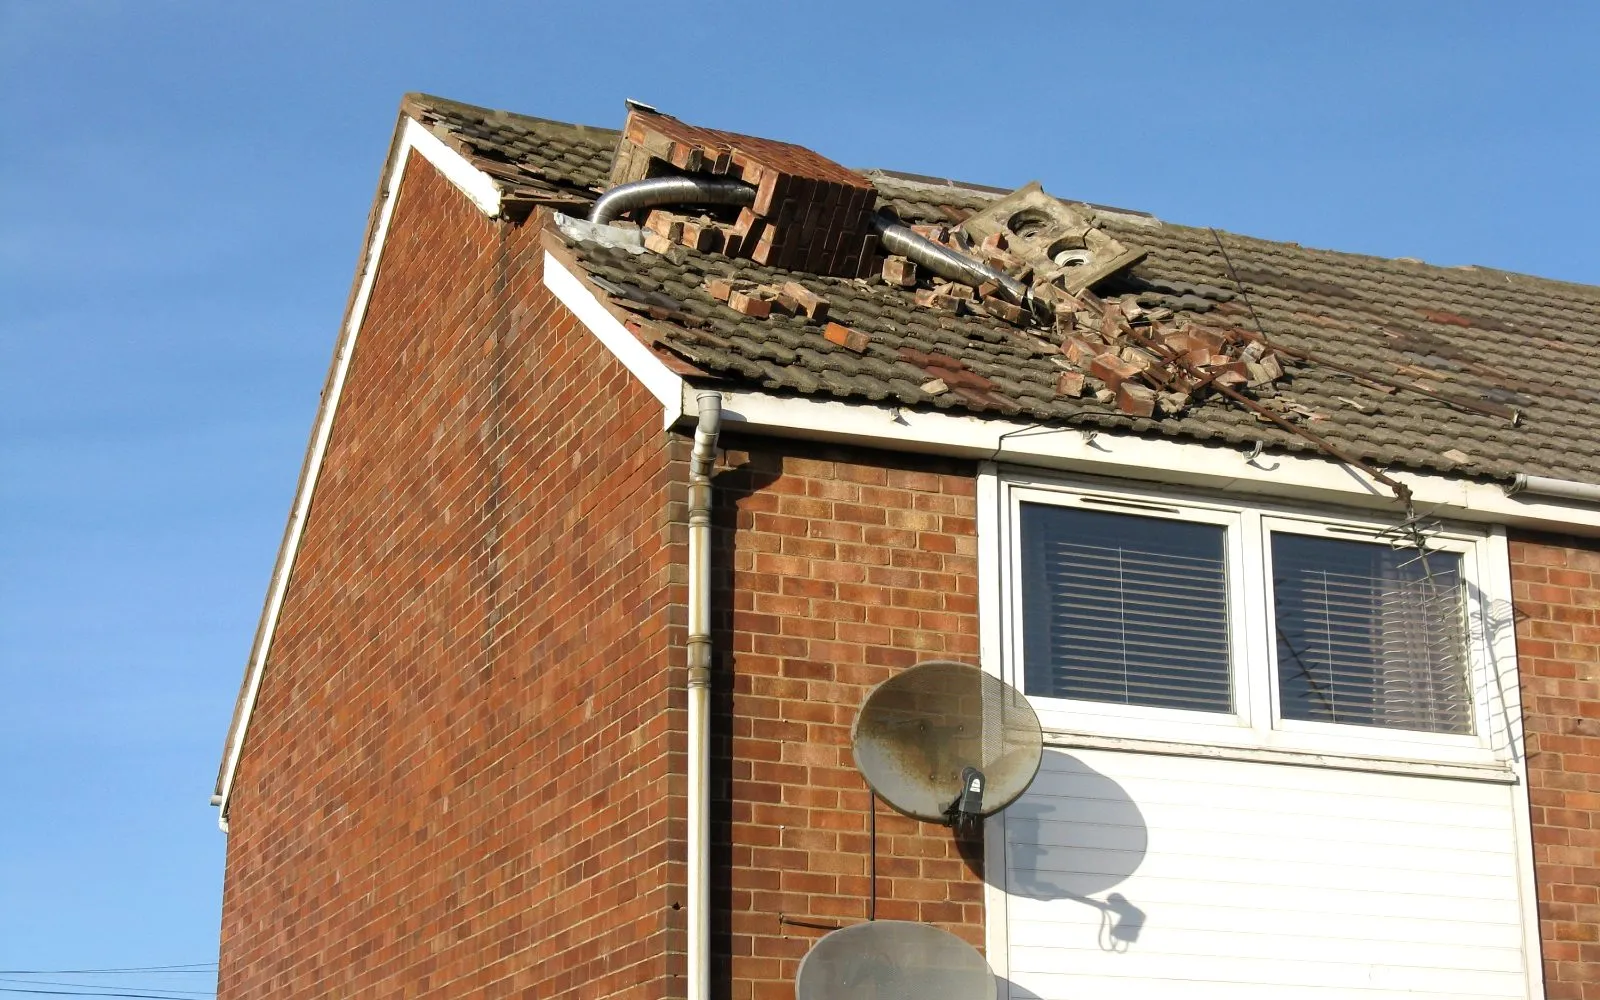
"Storm damaged chimney on Ferniehill Drive" by M J Richardson, CC BY-SA 2.0, via Wikimedia Commons
Home insurance does cover roof damage when a sudden event causes it, such as tiles blown off in a storm or a tree falling on the roof, but not damage from wear and tear or a lack of maintenance. The cause decides it, and your policy wording has the final say.
What buildings insurance usually covers on a roof
The roof is part of the structure, so it falls under buildings insurance. The Association of British Insurers lists the usual perils a home policy covers as fire, storm, flood, subsidence, burst pipes and water damage, theft and malicious damage (ABI, home insurance).
For a roof, that usually means tiles blown off by a storm, a chimney pot brought down by high winds, a tree falling onto the roof, and the water that then damages ceilings. Soaked carpets and furniture are a contents claim. Accidental damage is covered only on some policies.
What it usually doesn't cover
Insurers pay for sudden damage, not for a roof wearing out. The ABI says home insurance is not a maintenance contract, and gives "roof tiles not being replaced and the roof leaks when there is a storm" as damage that isn't covered.
The Financial Ombudsman names gradual damage and wear and tear as common exclusions (Financial Ombudsman, storm damage). On a roof, that typically means perished felt, weathered pointing, tiles slipping from rusted nails, or a leak that has dripped for months.
One rule is in your favour: the insurer has to prove an exclusion applies, for example with an inspection report.
How insurers and the Ombudsman decide a storm claim
The ABI reports that storm damage to homes paid out 32% more in 2025 than in 2024 (ABI, February 2026). Many disputes are about whether the weather really caused the damage.
The Ombudsman says a storm usually involves violent winds, usually with rain, hail or snow; some policies set their own wind-speed or rainfall figures. When a refused storm claim reaches it, the Ombudsman asks three questions:
- Was there a storm on the date the damage happened?
- Is the damage consistent with what storms generally cause?
- Was the storm the main cause, or would the damage have happened anyway?
The third is where old roofs fail: if the wind only finished off loose tiles, the insurer may call it wear and tear.
What to do after storm damage, before you claim
These steps follow the ABI's own storm advice (ABI, Storm Amy advice, October 2025). The aim is to stop the damage spreading and to keep a clear record of what happened, because the insurer, and the Ombudsman if you complain, will look at photos and reports. Don't wait for the insurer before making the house safe: a reasonable temporary repair is expected by insurers, and putting it off can make the damage worse.
Stay safe and stay off the roof
Keep people away from anything that could fall, and look from the ground.
Take photos first
Photograph the roof, the ceilings and any debris before anything is moved or fixed.
Contact your insurer early
Most insurers run a 24-hour helpline. Ask what they need from you.
Stop the water getting worse
Arrange temporary emergency repairs, but the ABI says speak to your insurer first. Keep every receipt.
Keep the damaged materials
Don't throw away broken tiles or soaked items too quickly, unless they're a danger to health.
Where a roofer fits into a claim
Your insurer may send its own surveyor or loss adjuster, or ask you for a roofer's quote before the permanent repair. Ask them which they want before work starts, other than stopping the water.
If water is coming in, call me on 07306 077999 any time, day or night, with no call-out charge. On an emergency I do a quick fix to stop the water, then come back for the proper repair, with a free written quote for it.
I don't deal with insurers on your behalf: the claim stays between you and your insurer.
If your claim is turned down
Ask the insurer to put the reason in writing and to name the exclusion it relies on. If you disagree, complain to the insurer first. If you don't get a final response within eight weeks, or you're unhappy with it, you can take it to the free Financial Ombudsman Service.
It helps to know which parts of the damage were the storm and which were wear: a claim can sometimes be accepted for part of the damage. Landlords: for most tenancies the roof is your repair, under section 11 of the Landlord and Tenant Act 1985.
Questions about insurance and roof damage
Does home insurance cover storm damage to a roof?
Yes, most buildings insurance policies cover storm damage to a roof, such as blown-off tiles or a fallen chimney pot, and the water damage that follows. The claim can be refused if the storm wasn't the main cause, for example because the tiles were already loose from age. Check your policy's definition of a storm.
Will my insurance pay to replace an old roof?
No, not just because it's old: replacing a worn-out roof is maintenance, which home insurance doesn't cover. An insurer pays for the damage a covered event caused, such as the slope a storm or falling tree damaged, and will look closely at what was wear and what was storm.
Do I need my insurer's permission before calling a roofer?
Not to stop water coming in: insurers expect you to limit the damage, and temporary emergency repairs are normal. The ABI advises speaking to your insurer first where you can and keeping the receipts. For the permanent repair, check whether the insurer wants to inspect first.
Related pages
Roof leaking? What to do right now
The first steps with water coming through the ceiling.
Emergency roofer, 24/7
Storm damage and leaks, day or night, with no call-out charge.
Roof repairs
Slipped, broken and missing tiles put right.
Landlords and letting agents
Roof repairs for rented homes, with tenant access arranged.
Storm damage to your roof? Call me
Ring 07306 077999, day or night, or WhatsApp me a photo. The visit is free, and I'll give you a written quote for the repair.
No call-out charge, day or night